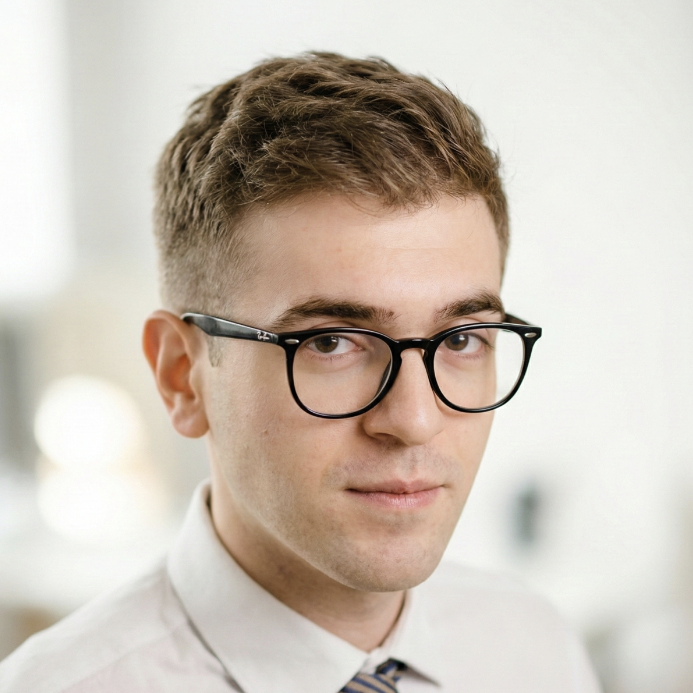
Federico Tropiano
PhD Researcher in Mathematical Finance
University of Genoa
I am a PhD researcher in Mathematical Finance working on stochastic processes, stochastic control, and quantitative models for financial markets.
My research focuses on the mathematical modeling of optimal trading problems, price impact, and market microstructure.
Research interests
- Stochastic control and HJB equations
- Optimal execution and market impact
- Quantitative finance
- Mathematical modeling of financial markets